A person earning six figures can still go broke. A person earning minimum wage can still build wealth. The difference usually isn’t income — it’s the invisible financial biases quietly steering every money decision behind the scenes.
You’ve probably met someone brilliant at their job who still can’t save a dollar. That’s not a math problem. It’s a psychology problem. Intelligence does not protect you from financial biases — in fact, smart people are often better at rationalizing bad money choices.
This article breaks down the psychology of money and exposes nine specific financial biases that keep everyday people stuck in the same cycle: earn, spend, regret, repeat. For each one, you’ll get a clear definition, a real-life example, and a practical fix you can start using today.
By the end, you’ll understand exactly how financial biases work inside your brain — and how to finally outsmart them.
Here’s the part that surprises most people: financial biases don’t feel like mistakes while they’re happening. They feel like common sense. That’s what makes them so dangerous. A bad decision driven by a bias comes wrapped in a story that sounds perfectly reasonable in the moment — “I deserve this,” “it’ll bounce back,” “everyone else is doing it.” The story is convincing precisely because your brain built it to protect your emotions, not your bank account.
This is also why reading about personal finance alone rarely fixes anyone’s money problems. You can know the math of compound interest and still fall for present bias at the checkout counter. You can understand diversification and still panic-sell during a market dip. Financial psychology, not financial literacy, is usually the missing piece — and that’s exactly the gap this guide is built to close.
What Are Financial Biases?
Financial biases are unconscious mental shortcuts that distort how we think about money. They cause otherwise smart people to make decisions that feel right in the moment but quietly damage their long-term wealth.
These patterns fall under a field called behavioral finance, which studies how psychology influences financial decision making. Unlike traditional economics, which assumes people act rationally, behavioral finance recognizes that emotions, habits, and mental shortcuts usually win.
Understanding your money mindset is the first step toward financial psychology mastery. Once you can name a bias, you can catch it before it costs you money. (Read our guide on building better financial habits.)
Why Your Brain Can Be Your Worst Financial Advisor
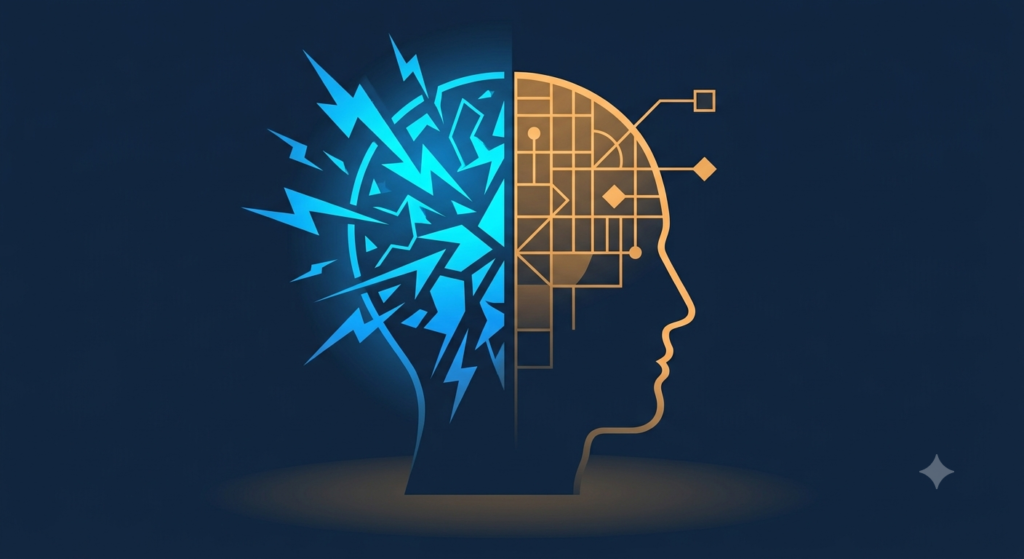
Your brain runs on two systems. System 1 is fast, automatic, and emotional. System 2 is slow, logical, and deliberate. Most financial biases live inside System 1.
When you swipe a credit card for something you don’t need, that’s System 1 talking. When you calmly compare interest rates before choosing a loan, that’s System 2 doing the work. The problem is that System 1 usually fires first, and System 2 often shows up too late — after the purchase is already made.
Emotions like fear, excitement, envy, and impatience hijack financial decision making constantly. A market dip triggers panic selling. A friend’s new car triggers a purchase you can’t afford. None of this is stupidity. It’s biology.
The good news: once you recognize these patterns, you can build systems that protect you from your own impulses. That’s exactly what the rest of this guide will help you do. (Read our guide on wealth mindset fundamentals.)
The Real Cost of Financial Biases Over Time
Financial biases rarely announce themselves as one dramatic mistake. Instead, they show up as small, repeated decisions that quietly compound in the wrong direction. A single skipped investment or one impulse purchase feels harmless. Ten years of the same pattern is a completely different story.
Consider two people who each earn the same income for a decade. One consistently gives in to present bias and instant gratification bias, spending extra income as soon as it arrives. The other builds simple systems around their financial biases and automates a portion of every paycheck into long-term investing.
| Behavior Pattern | Approximate 10-Year Outcome |
|---|---|
| Controlled by financial biases (spend first, save what’s left) | Minimal net worth growth, high dependence on next paycheck |
| Aware of financial biases (automated saving, delayed spending) | Meaningful investment growth through consistent contributions and compounding |
| Occasionally reactive (herd mentality during market swings) | Growth erased or reduced by poorly timed buying and selling |
| Consistent and rules-based (fixed investing schedule regardless of emotion) | Smoother, more predictable wealth accumulation over time |
The gap between these outcomes isn’t about income. It’s about which financial biases went unmanaged and which ones were caught early. This is precisely why behavioral finance experts argue that psychology, not income level, is the strongest predictor of long-term wealth.
It’s also worth noting that financial biases tend to cluster. Someone who struggles with lifestyle inflation often also struggles with instant gratification bias, since both are rooted in prioritizing the present moment. Recognizing one bias frequently makes it easier to spot the others hiding alongside it.
9 Financial Biases That Quietly Keep You Poor
These are the nine most common financial biases holding people back from real wealth. Some will feel painfully familiar.
1. Present Bias
Definition: Present bias is the tendency to overvalue immediate rewards while undervaluing future benefits.
Real-life example: You choose a $150 dinner out tonight instead of putting that money into a retirement account, even though you know compound growth would turn it into thousands over time.
Why it damages wealth: Present bias is one of the most destructive financial biases because it quietly cancels out decades of potential investment growth, one small decision at a time.
Practical solution: Automate your savings and investing so the “future you” decision happens before the “present you” ever sees the money.
Key takeaway: If a choice only benefits today, ask what it costs tomorrow.
2. Loss Aversion
Definition: Loss aversion is the tendency to feel the pain of losing money roughly twice as strongly as the pleasure of gaining the same amount.
Real-life example: An investor holds a losing stock far too long, refusing to sell, simply because selling would make the loss “real.”
Why it damages wealth: This bias causes people to avoid smart risks like long-term investing, and to cling to bad financial decisions instead of cutting losses early.
Practical solution: Set predetermined rules for when you’ll sell an investment or cut a loss, and follow them regardless of emotion.
Key takeaway: A loss you refuse to accept can grow into a much bigger one.
3. Confirmation Bias
Definition: Confirmation bias is the habit of seeking out information that supports what you already believe, while ignoring evidence that contradicts it.
Real-life example: Someone convinced a certain cryptocurrency will “definitely” moon only reads bullish posts and dismisses every warning sign.
Why it damages wealth: Confirmation bias blinds you to real risk, turning financial decision making into wishful thinking instead of analysis.
Practical solution: Deliberately seek out the strongest argument against your financial position before committing money to it.
Key takeaway: If you can’t explain why you might be wrong, you haven’t done your research.
4. Lifestyle Inflation
Definition: Lifestyle inflation happens when spending rises automatically alongside income, leaving little or nothing extra to save or invest.
Real-life example: A raise leads to a nicer apartment, a newer car, and pricier habits — and somehow the bank balance looks the same as before the raise.
Why it damages wealth: Among all financial biases, lifestyle inflation is uniquely dangerous because it disguises itself as normal progress instead of a problem.
Practical solution: Every time your income increases, direct a fixed percentage straight into savings or investments before adjusting your lifestyle.
Key takeaway: A bigger paycheck should build wealth, not just bigger bills.
5. Anchoring Bias
Definition: Anchoring bias is the tendency to rely too heavily on the first piece of information you receive when making a decision.
Real-life example: A shirt marked down from $200 to $80 feels like a bargain, even if it was never really worth more than $50.
Why it damages wealth: Anchoring distorts your sense of value, making overspending feel like a smart deal.
Practical solution: Research the actual market value of a purchase before looking at any “original” price or discount.
Key takeaway: The first number you see is a marketing tool, not the truth.
6. Herd Mentality
Definition: Herd mentality is the tendency to follow the crowd’s financial behavior instead of making an independent decision.
Real-life example: Everyone online is buying a hot stock, so you buy it too — right before the price crashes.
Why it damages wealth: Herd mentality is one of the riskiest financial biases because it replaces personal strategy with social pressure, often at the worst possible time.
Practical solution: Build a written investing plan in advance, and only make decisions that align with that plan — not the crowd’s mood.
Key takeaway: By the time everyone is talking about it, the opportunity is usually gone.
7. Overconfidence Bias
Definition: Overconfidence bias is the tendency to overestimate your own financial knowledge, skill, or ability to predict outcomes.
Real-life example: A new investor bets heavily on a single stock, certain they’ve “figured out” the market after one lucky win.
Why it damages wealth: This bias leads to concentrated, high-risk bets instead of diversified, long-term investing strategies.
Practical solution: Diversify every investment and treat any single prediction, including your own, with healthy skepticism.
Key takeaway: One good call doesn’t make you an expert — it makes you lucky once.
8. Status Quo Bias
Definition: Status quo bias is the preference to keep things exactly as they are, even when a change would clearly improve your finances.
Real-life example: Someone keeps thousands of dollars sitting in a low-interest savings account for years, simply because moving it feels like effort.
Why it damages wealth: Of all the financial biases on this list, status quo bias is the quietest — it costs money purely through inaction.
Practical solution: Schedule a recurring financial review, at least twice a year, specifically to challenge decisions you’ve been avoiding.
Key takeaway: Doing nothing is still a financial decision, and it isn’t always the safe one.
9. Instant Gratification Bias
Definition: Instant gratification bias is the strong pull toward quick pleasure now, even when it works directly against your bigger financial goals.
Real-life example: A payday triggers an impulse purchase instead of a transfer into an investment account, even though the goal was set just days earlier.
Why it damages wealth: This bias undermines budgeting, saving, and long-term investing by rewarding short-term comfort over long-term financial freedom.
Practical solution: Add a mandatory 24-hour waiting period before any non-essential purchase over a set amount.
Key takeaway: Delayed gratification is one of the most underrated build wealth habits you can practice.
How to Train Your Brain for Better Financial Decisions
Recognizing financial biases is only step one. Building systems that protect you from them is what actually changes your financial life.
Willpower alone rarely beats financial biases, because willpower is inconsistent and biases are constant. The people who successfully build wealth usually aren’t more disciplined than everyone else — they’ve simply removed the moment of decision from the equation. When a system handles the choice automatically, a bias never gets the chance to argue.
That’s the underlying goal of every strategy below: reduce how often you have to rely on in-the-moment self-control, and increase how often good financial decisions happen by default.
- Automate savings so wealth-building happens without relying on willpower.
- Practice long-term investing instead of reacting to short-term market noise. (Read our guide on long-term investing strategy.)
- Budget with intention by giving every dollar a specific job before the month begins.
- Track spending consistently so patterns and biases become visible instead of invisible.
- Create financial rules in advance, like spending limits or cooling-off periods, so emotional decisions have less room to operate.
- Delay emotional purchases by waiting at least 24 to 48 hours before buying anything unplanned.
- Review financial decisions regularly, treating your money like a business that needs a monthly audit. (Read our guide on budgeting with intention.)
Each of these habits directly counters one or more financial biases, replacing emotional reactions with a repeatable system.
Common Signs You’re Being Controlled by Financial Biases
Most people assume financial biases only affect other people — the impulsive spender, the panicked investor, the friend who always seems to be broke despite a good salary. In reality, financial biases operate quietly enough that even careful, financially literate people miss them in their own behavior.
Use this checklist to self-assess how much financial biases are influencing your daily decisions:
- You regularly buy things you can’t fully explain the reason for.
- Your savings rate hasn’t changed even though your income has grown.
- You avoid checking your bank account or investment balances.
- You’ve held onto a losing investment “just in case it turns around.”
- You copy other people’s financial moves without independent research.
- You feel pressure to keep up with friends’ or influencers’ spending.
- You put off financial decisions for months at a time.
- You feel a rush of excitement before a purchase and regret shortly after.
If you recognized yourself in three or more of these, financial biases are likely shaping more of your money life than you realized — and that’s exactly why awareness matters.
Final Thoughts
Financial biases aren’t a character flaw. They’re a normal part of being human, wired into how our brains evolved to handle risk, reward, and uncertainty. The goal was never to eliminate them completely — that’s not realistic.
The real goal is awareness. Once you can name present bias, loss aversion, or lifestyle inflation in real time, you gain the power to pause before you act. That pause is where better financial decisions are made.
Start with one bias from this list. Build one system to counter it. Small, consistent changes in your money mindset compound into real wealth over time — the same way an unaddressed bias compounds into real financial damage. (Read our guide on wealth mindset and digital income streams.)
Nobody eliminates financial biases entirely, and that was never the point of this guide. The people who build lasting wealth aren’t the ones who never feel tempted by present bias or lifestyle inflation — they’re the ones who built enough structure around their money that temptation rarely gets the final vote. Pick one system from this article, put it in place this week, and let time do the rest.
FAQ Section
1. What are financial biases?
Financial biases are unconscious mental shortcuts that distort financial decision making, causing people to make choices that feel right immediately but hurt their long-term wealth.
2. What is the most common financial bias?
Present bias and instant gratification bias are among the most common financial biases, both driving people to prioritize short-term comfort over long-term financial goals.
3. How do financial biases affect investing?
Financial biases like loss aversion, overconfidence, and herd mentality often push investors toward panic selling, risky concentrated bets, or copying the crowd instead of following a sound long-term investing strategy.
4. Can financial biases be unlearned?
Financial biases can’t be fully eliminated, but their impact can be greatly reduced through awareness, automated systems, and consistent financial habits.
5. How does behavioral finance relate to financial biases?
Behavioral finance is the field of study that examines financial biases and other psychological patterns that influence real-world financial decision making.
6. What’s the simplest way to fight financial biases?
Automating savings and investing removes many financial biases from the equation entirely, since decisions happen before emotional impulses can interfere.