Most people work hard their entire lives and still never build real wealth. They earn a paycheck, pay their bills, and hope that whatever is left over will somehow turn into financial freedom. It rarely does.
Here’s the uncomfortable truth: earning money and building wealth are two completely different skills. You can make a six-figure income and still be broke. You can make an average salary and still retire wealthy. The difference isn’t luck. It’s whether you understand and apply the wealth formula — a simple system that shows exactly how income, savings, and investing work together to create lasting financial freedom.
This article breaks down the wealth formula in plain language, with real examples, so you can start applying it today, no matter how much you currently earn.
The Wealth Formula
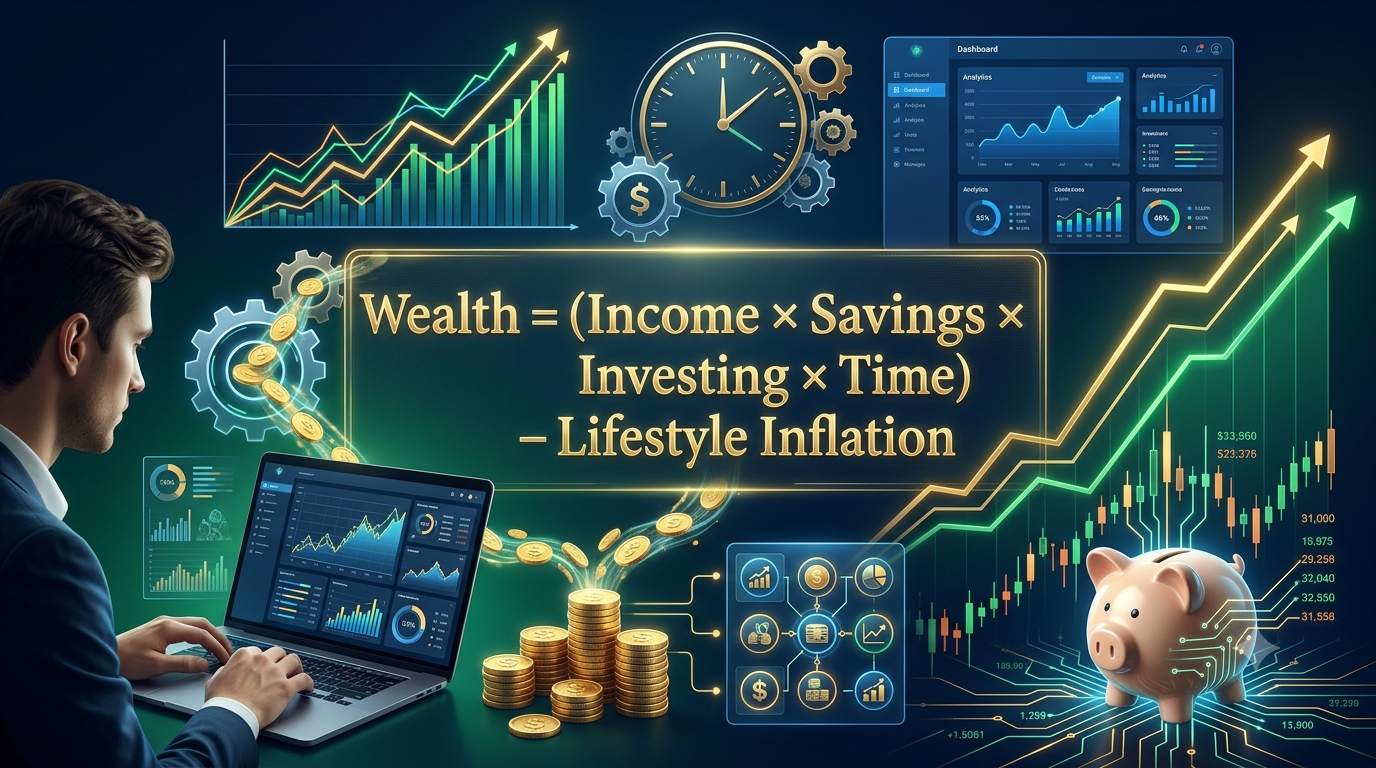
Wealth doesn’t come from one single habit. It comes from four forces working together, minus one force working against you. That relationship can be written as a simple formula:
Wealth = (Income × Savings Rate × Investing Return × Time) – Lifestyle Inflation
Let’s break that down in plain English:
- Income is the money you bring in from work, business, or other sources.
- Savings Rate is the percentage of that income you keep instead of spend.
- Investing Return is how much your saved money grows over time.
- Time is how many years you let this process run.
- Lifestyle Inflation is the silent force that increases your spending every time your income rises, quietly canceling out your progress.
When these four positive forces increase together, and lifestyle inflation is kept low, wealth builds — often faster than people expect. When even one factor is missing, like when someone saves money but never invests it, or invests but has no savings rate to fund it, the formula breaks down and wealth-building stalls.
The wealth formula isn’t about being rich or poor. It’s about understanding that wealth is the product of a system, not a single decision.
Why Most People Never Build Wealth
If wealth-building were only about earning more money, every high-income earner would be wealthy. That’s not what happens. Studies on personal finance behavior consistently show that spending habits, not income level, are the strongest predictor of long-term wealth.
Here are the most common reasons people never break through, despite years of steady paychecks.
Spending everything earned. Many people operate on a simple, dangerous rule: spend what you earn, and maybe save what’s left. The problem is there’s rarely anything left. Without a plan, income disappears into everyday expenses.
Lifestyle inflation. Every time income rises — a raise, a bonus, a new job — spending quietly rises with it. A bigger apartment, a nicer car, more takeout. The paycheck grows, but the gap between income and spending stays the same, or shrinks.
No investing. Some people save diligently but never invest. Their money sits in a low-interest savings account, slowly losing value to inflation instead of growing through compound interest.
Saving without investing. This is a close cousin to the mistake above. Saving protects money. Investing grows it. Without investing, savings alone can never outpace inflation or build meaningful long-term wealth.
Depending on one income source. Relying entirely on a single paycheck is risky. One layoff, one health issue, or one economic downturn can derail years of progress. Diversifying income, even in small ways, adds stability.
Short-term thinking. Wealth-building is a decades-long game, but most financial decisions are made with a weeks-long mindset. Choosing instant gratification over long-term growth, again and again, is one of the biggest wealth killers there is.
“Wealth isn’t built by a single big decision. It’s built by hundreds of small decisions, repeated consistently, over a long period of time.”
Income: The Engine of Wealth
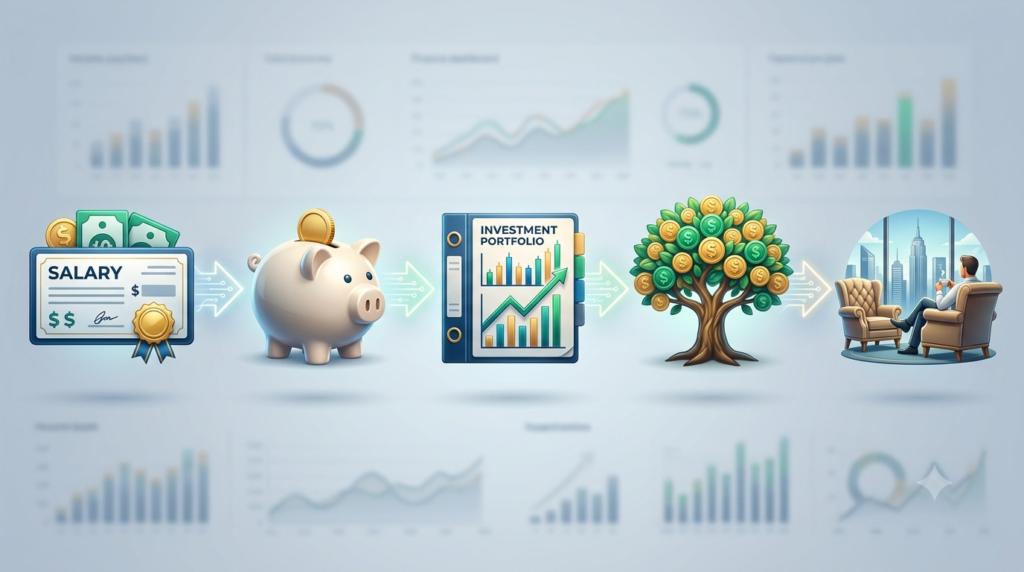
Income is where the wealth formula starts. Without income, there’s nothing to save or invest. But income is only the engine of the wealth formula — it powers the system, but it doesn’t guarantee the destination.
Active income is money earned in direct exchange for your time, such as a salary, hourly wage, or freelance work. It’s the most common starting point, but it has a ceiling: there are only so many hours in a day.
Side income comes from work done outside a primary job — freelancing, consulting, tutoring, or a part-time service business. It adds a second stream without requiring a career change.
Digital income includes things like content creation, digital products, online courses, or affiliate marketing. It often takes longer to build but can eventually generate income with less ongoing time investment than active work.
Earning power grows through deliberate effort, not luck. A few proven ways to increase it:
- Build in-demand skills through courses, certifications, or hands-on projects
- Negotiate salary increases based on documented results, not tenure alone
- Take on higher-responsibility roles that come with higher pay
- Start a side income stream aligned with an existing skill
- Track industry salary benchmarks so you know your market value
Here’s the part many people miss: income is only one variable in the formula. A person earning $150,000 a year who saves nothing and invests nothing will build less wealth over 20 years than someone earning $60,000 who saves 25% and invests consistently. Income creates the opportunity for wealth. It doesn’t create wealth by itself.
Before chasing a raise or a new income stream, calculate what percentage of your current income you’re actually keeping. If it’s close to zero, more income will likely just mean more spending, not more wealth.
Savings Rate: The Accelerator
If income is the engine of the wealth formula, savings rate is the accelerator. It determines how much fuel actually gets converted into forward motion.
Two people can earn the same income and end up in completely different financial positions, based entirely on their savings rate. Someone who saves 10% of their income will need roughly three times longer to reach financial independence than someone who saves 30%, because a higher savings rate does two things at once: it builds a bigger investment pool, and it lowers the amount of money needed to sustain their future lifestyle.
Before aggressive saving or investing, most financial educators recommend setting aside three to six months of essential expenses in an easily accessible account. This fund acts as a buffer so that a job loss or unexpected expense doesn’t force you to sell investments at the wrong time or go into debt.
Instead of saving whatever is left at the end of the month, reverse the order: move a fixed percentage of income into savings and investments the moment it arrives, before any spending happens. What’s left becomes the spending budget, not the other way around.
A few beginner-friendly budgeting systems worth considering:
| System | How It Works | Best For |
|---|---|---|
| 50/30/20 Rule | 50% needs, 30% wants, 20% savings/investing | Beginners who want a simple starting point |
| Zero-Based Budget | Every dollar is assigned a job before the month starts | People who want full control and visibility |
| Pay-Yourself-First | Savings and investing are automated before spending | People who want savings to happen automatically |
A practical example: if someone earns $4,000 a month and saves $600 (a 15% savings rate), and then gets a raise to $4,800 a month, keeping spending flat and saving the extra $800 pushes their savings rate to roughly 29% — nearly doubling the output of their personal wealth formula, without any change in lifestyle.
Investing: The Multiplier
Savings alone builds a pile of money. Investing turns that pile into a growing one. This is the multiplier in the wealth formula, and it’s the step most beginners delay the longest, usually out of fear or lack of knowledge. Investing is what separates a stalled wealth formula from one that’s actually compounding.
Compound interest is what happens when your investment returns start earning their own returns. Imagine investing $1,000 that grows by 8% in a year — you now have $1,080. The next year, that 8% growth applies to $1,080, not just the original $1,000. Over decades, this snowball effect becomes the single most powerful force in the wealth formula.
Stocks represent partial ownership in individual companies. They offer high growth potential but come with higher risk tied to a single company’s performance.
ETFs (Exchange-Traded Funds) bundle many stocks or assets into a single investment, spreading risk across dozens or hundreds of companies at once.
Index funds track a broad market index, such as a total stock market index, offering low-cost, diversified, long-term growth with minimal active management required.
Digital assets, such as cryptocurrency, are a newer and higher-risk category. They can be part of a diversified strategy for investors who understand the volatility involved, but they should generally represent a small portion of a beginner’s portfolio.
Every investment carries some level of risk, and generally, higher potential returns come with higher potential volatility. The goal isn’t to avoid risk entirely — it’s to match the level of risk to your timeline and comfort level, and to diversify so no single investment can derail your progress.
Markets fluctuate in the short term but have historically trended upward over long periods. Long-term investing allows a portfolio to ride out short-term dips and benefit from decades of compound growth, rather than trying to predict day-to-day price movements.
Time: The Secret Ingredient
Time is the variable in the wealth formula that people underestimate the most, because its effects are invisible in the short term and enormous in the long term.
Consider two people. Person A invests $300 a month starting at age 25 and stops at age 35, investing for just 10 years, then leaves the money untouched. Person B waits until age 35 to start, investing $300 a month for 30 years straight, until age 65. Assuming an average annual return of 8%:
- Person A invests $36,000 total but ends up with roughly $470,000 by age 65
- Person B invests $108,000 total — three times more — but ends up with roughly $408,000 by age 65
Person A invested less money overall but ended up with more, purely because they started earlier and let compounding run longer.
This example illustrates a core truth of the wealth formula: time doesn’t just add to your results, it multiplies them. The earlier money is invested, the more compounding cycles it goes through, and each cycle builds on the last.
Trying to perfectly time the market — buying only at the lowest points — is nearly impossible to do consistently, even for professional investors. Investing a fixed amount on a regular schedule, regardless of market conditions, tends to outperform the stress and guesswork of market timing over the long run.
Lifestyle Inflation: The Wealth Killer
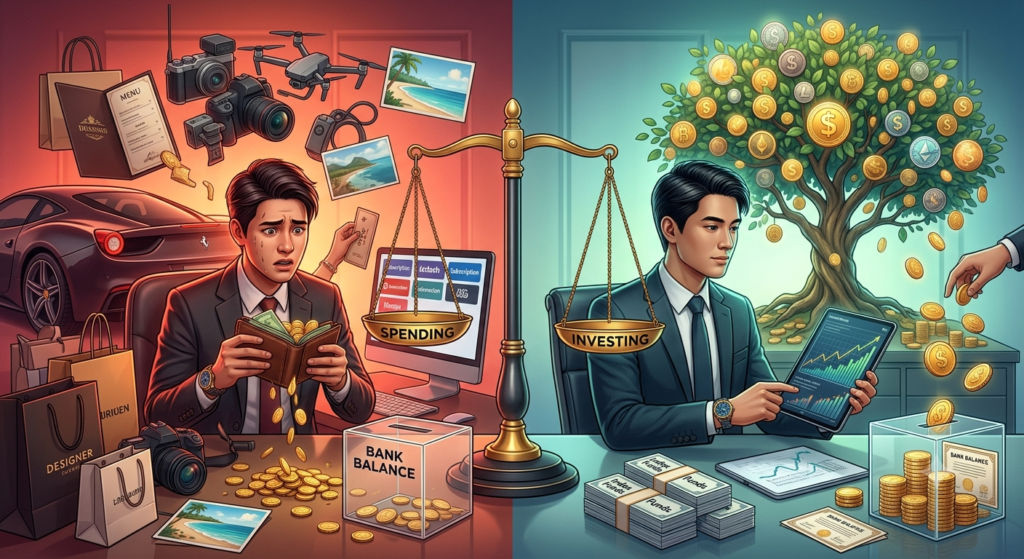
Lifestyle inflation is the one part of the wealth formula working against you, and it’s the reason so many high earners still live paycheck to paycheck.
As income rises, spending naturally follows unless a person makes a deliberate decision to prevent it. A bigger apartment feels justified. A nicer car feels earned. Individually, each upgrade seems reasonable. Together, they quietly erase the extra income that could have gone toward savings and investing.
Constant exposure to other people’s vacations, purchases, and lifestyles creates a comparison trap. What looks like effortless wealth online is often financed by debt, and chasing that image can push real spending far beyond what’s sustainable.
Social comparison is one of the oldest wealth killers there is. Spending decisions driven by what others have, rather than personal financial goals, consistently lead to weaker long-term outcomes.
A few ways to avoid it:
- Automate savings and investing increases before spending increases
- Wait 30 days before making non-essential large purchases
- Set a personal “lifestyle cap” tied to specific financial milestones, not income
- Track net worth over time instead of comparing lifestyles with peers
- Celebrate income increases by increasing your investing rate first
Create Your Own Wealth Formula
Understanding the wealth formula is one thing. Applying it consistently is what actually builds wealth. Here’s a simple five-step framework for putting your own wealth formula into action:
Step 1: Increase income. Look for one realistic way to grow your income this year, through a raise, a skill upgrade, or a side income stream.
Step 2: Save 20% (or more). Set a savings rate target and automate it so it happens before spending, not after.
Step 3: Invest monthly. Choose a diversified, low-cost investment approach and contribute on a fixed schedule.
Step 4: Stay consistent. Keep contributing through market ups and downs. Consistency matters more than perfect timing.
Step 5: Avoid lifestyle inflation. Every time income rises, direct a portion of the increase toward investing before lifestyle spending grows.
Repeat for years.
Here’s how each factor affects long-term wealth:
| Scenario | Monthly Savings | Annual Return | Years | Estimated Result |
|---|---|---|---|---|
| Low effort | $100 | 5% | 20 | ~$41,000 |
| Moderate effort | $300 | 8% | 20 | ~$177,000 |
| High effort | $600 | 8% | 30 | ~$894,000 |
| High effort, started early | $600 | 8% | 40 | ~$2,000,000+ |
The table shows a clear pattern: increasing the savings amount, the investing return, and especially the time horizon compounds results dramatically. Small, consistent improvements in each factor of the wealth formula produce outsized long-term outcomes, which is exactly why the wealth formula rewards patience over perfection.
Common Wealth Myths
“You must be rich to invest.” Many investment platforms today allow people to start with small, regular contributions. Building wealth through investing starts with consistency, not a large initial sum.
“Saving alone builds wealth.” Savings protect money from loss but don’t grow it meaningfully. Without investing, saved money can actually lose purchasing power to inflation over time.
“Investing is gambling.” Gambling involves short-term, high-risk bets with no underlying strategy. Long-term, diversified investing is based on historical market growth patterns and time-tested principles, not chance.
“It’s too late to start.” While starting early has clear advantages, starting at any age is better than not starting at all. A 45-year-old who begins investing consistently today will be in a far stronger position in 20 years than one who waits any longer.
“Wealth is only for entrepreneurs.” Employees who apply the wealth formula — increasing income, maintaining a high savings rate, investing consistently, and giving it time — can build significant wealth without ever starting a business.
Your 30-Day Wealth Formula Action Plan
This 30-day plan is designed to help you put the wealth formula into practice, one week at a time.
Week 1: Assess. Calculate your current income and expenses, determine your current savings rate, and review any existing investment accounts.
Week 2: Build the foundation. Open a high-yield savings account if you don’t have one, start or top up an emergency fund, and choose a budgeting system that fits your lifestyle.
Week 3: Start investing. Open a retirement or brokerage account if you don’t already have one, research low-cost, diversified investment options, and set up your first automatic monthly contribution.
Week 4: Automate and commit. Automate your savings and investing contributions, set a lifestyle inflation rule for future raises or income increases, and schedule a monthly money check-in for the months ahead.
Conclusion
Real wealth isn’t built by a lucky break, a big salary, or a hot investment tip. It’s built by understanding and applying a simple, repeatable formula: grow your income, save a meaningful percentage of it, invest that savings wisely, give it time to compound, and keep lifestyle inflation in check along the way.
The wealth formula works the same way for everyone, regardless of starting point. What changes is how consistently each person applies the wealth formula. Start where you are, with what you have, and let the wealth formula do what it’s designed to do — turn small, consistent actions into lasting financial freedom.
The best time to apply the wealth formula was years ago. The second-best time is today.
Frequently Asked Questions
What is the wealth formula?
The wealth formula is a framework showing that wealth equals income multiplied by savings rate, investing return, and time, minus lifestyle inflation.
Can I build wealth on a low income?
Yes. A high savings rate and consistent investing, even on a modest income, can outperform a high income with no savings or investing habits.
Is investing risky?
All investing carries some risk, but long-term, diversified investing has historically been one of the most reliable ways to grow wealth over decades.
What’s the difference between saving and investing?
Saving preserves money in a low-risk, low-growth account. Investing puts money into assets designed to grow in value over time.
What’s the difference between saving and investing?
Saving preserves money in a low-risk, low-growth account. Investing puts money into assets designed to grow in value over time.
At what age should I start investing?
The earlier, the better, but there is no age at which it becomes too late to benefit from consistent investing.
Do I need a lot of money to start investing?
No. Many investment platforms allow beginners to start with small, regular monthly contributions.
How long does it take to build real wealth?
It varies by income, savings rate, and investment returns, but most people following the wealth formula consistently see meaningful results over 10 to 20 years.