Most people don’t fail at building wealth because they lack money. They fail because they never had a we7 Proven Wealth Building Blueprint Steps for Amazing Results
Most people don’t fail at building wealth because they lack money. They fail because they never had a wealth building blueprint to begin with. They buy a stock because a friend mentioned it. They jump into crypto because a video went viral. They chase whatever looks exciting that week, and a year later, they’re right back where they started — confused, discouraged, and no closer to financial freedom.
A real wealth building blueprint isn’t about guessing right. It’s about following a repeatable system that works whether markets are up or down, whether crypto is trending or crashing, and whether you’re 22 or 42. In this guide, you’ll learn exactly what a wealth building blueprint is, how stocks, cryptocurrency, and digital assets each play a role in it, and the 7 concrete steps you can start applying today — even if you’re starting with very little money.
This is not financial advice. It’s an educational framework built on long-established investing principles, historical evidence, and common sense. What you do with it is up to you.
Think of a wealth building blueprint the same way an architect thinks of a blueprint for a house. You wouldn’t start pouring concrete without a plan, and you shouldn’t start investing without one either. A wealth building blueprint tells you where your money goes first, how much risk each part of your plan can absorb, and what order to build things in so one step supports the next. Without that structure, even a good income can leak away into random purchases, impulsive trades, and missed opportunities.
The reason a wealth building blueprint matters more today than ever is choice. A generation ago, the average beginner had a handful of investment options: a savings account, maybe a company pension, maybe a few stocks through a broker. Today, you can open an app and buy fractional shares, cryptocurrency, or launch a digital storefront within minutes. That much choice without a wealth building blueprint isn’t freedom — it’s overwhelm. This guide exists to turn that overwhelm into a clear, ordered plan you can actually follow.
What Is a Wealth Building Blueprint?
Definition: A wealth building blueprint is a structured, long-term plan for growing your net worth by combining consistent saving, strategic investing, and multiple income-generating assets — rather than relying on a single source of income or a single investment.
Every beginner investor eventually asks the same question: where should my money actually go? Without a blueprint, the answer usually comes from whatever is loudest that month — a hot stock tip, a trending coin, a “get rich” course. That’s not a strategy. That’s noise.
A wealth building blueprint solves this by giving you a framework to evaluate every financial decision against. Instead of asking “should I buy this?” you start asking “does this fit my plan?” That single shift in thinking is often the difference between someone who builds wealth over a decade and someone who’s still starting over ten years later.
Diversification matters here because no single asset class is guaranteed to perform well every year. Stocks can have flat decades. Crypto can swing 70% in either direction within months. A wealth building blueprint spreads your risk across asset types so that a downturn in one area doesn’t wipe out your entire financial future.
A good wealth building blueprint also removes decision fatigue. Instead of re-evaluating your entire financial life every time the market moves or a new coin trends on social media, you simply check the move against your existing plan. Does it fit your risk tolerance? Does it match your timeline? Does it fit inside your existing allocation? If not, you skip it — no debate required. That’s the quiet power of having a wealth building blueprint: it turns hundreds of small financial decisions into a handful of simple, repeatable rules.
Why Wealth Is Built Through Assets, Not Income Alone
A common misconception is that a bigger paycheck automatically means more wealth. It doesn’t. Income is what comes in; assets are what you own that can grow in value or generate money independently of your labor.
Active income requires your direct time — a job, freelance work, a service-based business. The moment you stop working, it stops paying. Passive income, by contrast, comes from assets: dividend-paying stocks, rental property, a digital product that sells while you sleep, or interest from investments.
Wealthy individuals aren’t necessarily the highest earners — they’re usually the ones who converted a portion of their income into appreciating assets early and consistently. This is why investing should never be viewed as optional or something to “get to later.” It’s the mechanism that turns temporary income into lasting wealth. Earning pays the bills today; owning assets is what builds financial freedom over the next 10, 20, or 30 years.
This distinction is exactly why a wealth building blueprint puts assets at its center rather than income alone. A high salary without an investing plan can still leave someone financially fragile, while a modest income paired with a consistent wealth building blueprint can quietly outgrow it over time. The goal of your wealth building blueprint isn’t to replace your income — it’s to put a portion of every dollar you earn to work so that, eventually, your assets are generating money even while you sleep.
Understanding the Three Wealth-Building Assets
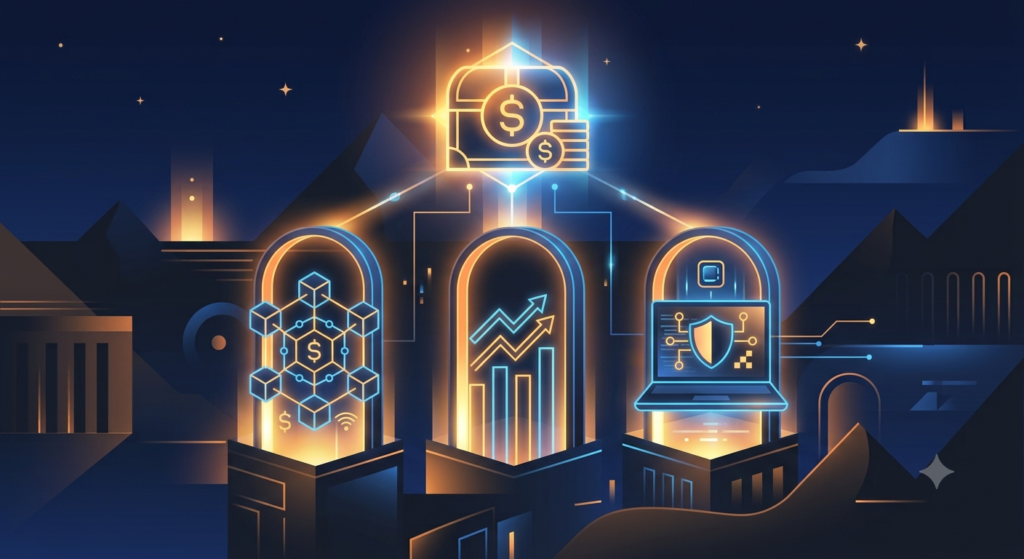
A modern wealth building blueprint typically rests on three categories of assets. Each has a different risk profile, time horizon, and role in your overall portfolio. Understanding what each one actually does — rather than just chasing whichever is trending — is the foundation every solid wealth building blueprint is built on.
Stocks
Stocks represent partial ownership in a publicly traded company. When you buy a share, you own a small slice of that business, including a claim on its future profits and growth.
Advantages: Stocks have historically been one of the most reliable long-term wealth-building vehicles available to everyday investors. Broad market index funds have delivered strong average annual returns over multi-decade periods, according to data widely cited by sources like Vanguard and Morningstar, though past performance never guarantees future results. Stocks are also highly liquid, regulated, and accessible through low-cost brokerage accounts.
Risks: Individual stocks can be volatile in the short term, and picking single companies carries concentration risk. Even diversified stock portfolios can drop significantly during recessions or market corrections.
Who should invest: Nearly every long-term investor benefits from having stock market exposure, particularly through diversified vehicles like index funds and ETFs, because they reduce single-company risk while still capturing broad economic growth.
Cryptocurrency
Cryptocurrency is a digital, decentralized form of asset built on blockchain technology. Bitcoin, the first and most well-known cryptocurrency, was designed as a decentralized store of value. Ethereum expanded on this idea by enabling smart contracts and decentralized applications.
Opportunities: Crypto offers exposure to an emerging asset class and technology that some investors believe could reshape parts of finance and digital ownership over the long run.
Risks: Cryptocurrency is significantly more volatile than traditional stocks. Prices can swing dramatically within days based on sentiment, regulation, or macroeconomic news. Unlike stocks, most cryptocurrencies don’t represent ownership in a cash-flow-generating business, which makes valuation far more speculative.
Long-term perspective: Because of this volatility, crypto is best treated as a small, deliberate allocation within a diversified blueprint rather than a primary wealth-building vehicle, especially for beginners.
Digital Assets
Digital assets are online properties or products you build and own that can generate income over time. Examples include websites, blogs, YouTube channels, online courses, digital products like templates or eBooks, software tools, and AI-powered businesses.
Unlike stocks or crypto, digital assets require upfront time and skill investment rather than just capital. But once built, they can produce recurring income with relatively low ongoing costs, and you retain full ownership and control — something you don’t get with a traditional job. For beginners with more time than money, digital assets are often the most accessible entry point into building real wealth.
This is precisely why digital assets deserve equal weight in any modern wealth building blueprint, rather than being treated as a side hustle or afterthought. Stocks and crypto require you to already have capital to invest; digital assets let you generate that capital in the first place, using skills and time you already have. For many beginners, building a digital asset is the missing piece that funds the rest of their wealth building blueprint — the stock investing, the crypto allocation, and eventually, financial independence.
The 7-Step Wealth Building Blueprint
This is the core framework. Each step builds on the one before it, and skipping steps is one of the most common reasons beginners stall out. Follow this wealth building blueprint in order, and resist the urge to jump straight to Step 3 or Step 4 just because stocks and crypto feel more exciting than an emergency fund.
Step 1: Build an Emergency Fund
Before you invest a single dollar in stocks, crypto, or a digital business, set aside 3–6 months of essential living expenses in an accessible, low-risk account. This fund protects your investments from being sold off in a panic if you lose your job or face an unexpected expense. Without this cushion, a single emergency can force you to liquidate investments at the worst possible time.
Skipping this step is one of the most common ways a wealth building blueprint falls apart before it even gets started. An emergency fund isn’t exciting, and it won’t grow your net worth the way stocks or digital assets eventually will — but it’s what keeps the rest of your plan intact when life doesn’t go as expected.
Step 2: Invest in Yourself Through High-Income Skills
Your own earning capacity is often your greatest asset early on. Developing high-income skills — such as digital marketing, copywriting, coding, sales, or data analysis — increases the amount of capital you have available to invest. The more you can earn, the faster you can fund the rest of this blueprint.
For anyone just starting out, this step often has the highest return on investment in the entire wealth building blueprint. A raise, a new skill, or a higher-paying freelance client can free up more monthly capital than years of small tweaks to your investment portfolio, giving every later step in your wealth building blueprint more fuel to work with.
Step 3: Invest Consistently in Stocks
Once your emergency fund is in place, begin investing regularly in the stock market. For most beginners, low-cost index funds and ETFs offer instant diversification across hundreds or thousands of companies, reducing the risk tied to picking individual stocks.
Use dollar-cost averaging — investing a fixed amount on a regular schedule regardless of market conditions. This removes the pressure of trying to “time the market” and smooths out the impact of volatility over time. Consistency, not perfect timing, is what compounds into long-term investing success.
Stock investing is typically the largest and most stable pillar of a wealth building blueprint, which is why it’s placed early in the sequence. Automating your contributions — so a fixed amount moves into your investment account every payday — makes this step of your wealth building blueprint effortless to maintain, even during months when the market feels uncertain.
Step 4: Use Crypto as a High-Risk, High-Reward Allocation
If you choose to include cryptocurrency in your blueprint, treat it as a deliberate, limited allocation — many conservative investors cap speculative assets at a small single-digit percentage of their total portfolio. This isn’t about avoiding crypto entirely; it’s about responsible allocation rather than speculation. Never invest money in crypto that you can’t afford to lose, and avoid chasing coins based on hype alone.
Step 5: Build Digital Assets That Produce Income
Start building at least one digital asset — a blog, a niche content channel, a simple digital product, or an AI-assisted service. This step connects directly to entrepreneurship: unlike stocks or crypto, digital assets let you actively create value rather than just purchase it. Over time, a well-built digital asset can produce meaningful passive income that supplements your stock and crypto investments.
This is often the step that separates a basic savings plan from a genuine wealth building blueprint. Anyone can open a brokerage account, but building an asset you fully own and control adds a growth engine to your plan that isn’t tied to market conditions at all.
Step 6: Diversify Your Portfolio
Spread your capital across asset types, industries, and risk levels. Diversification doesn’t guarantee against loss, but it significantly reduces the chance that a single bad outcome derails your entire financial plan. Revisit your asset allocation periodically and adjust it as your goals, income, and risk tolerance evolve over time.
Rebalancing is what keeps a wealth building blueprint aligned with its original intent. If crypto grows to make up a much larger share of your portfolio than planned, rebalancing brings your wealth building blueprint back to its intended risk level instead of letting one volatile asset quietly take over your entire plan.
Step 7: Stay Consistent and Let Compound Growth Work
Wealth building is not a sprint. Compound growth rewards patience and discipline far more than it rewards intelligence or timing. The investors who build the most wealth over decades are rarely the ones who found the “perfect” investment — they’re the ones who stayed invested, kept contributing, and avoided emotional decisions during market swings. Consistency is the single most underrated wealth-building skill.
This final step is what ties the entire wealth building blueprint together. Steps 1 through 6 only work if you keep repeating them, year after year, regardless of what the news or social media is saying about markets that week. A wealth building blueprint isn’t something you complete once — it’s something you return to, again and again, until it becomes second nature.
Stocks vs Crypto vs Digital Assets
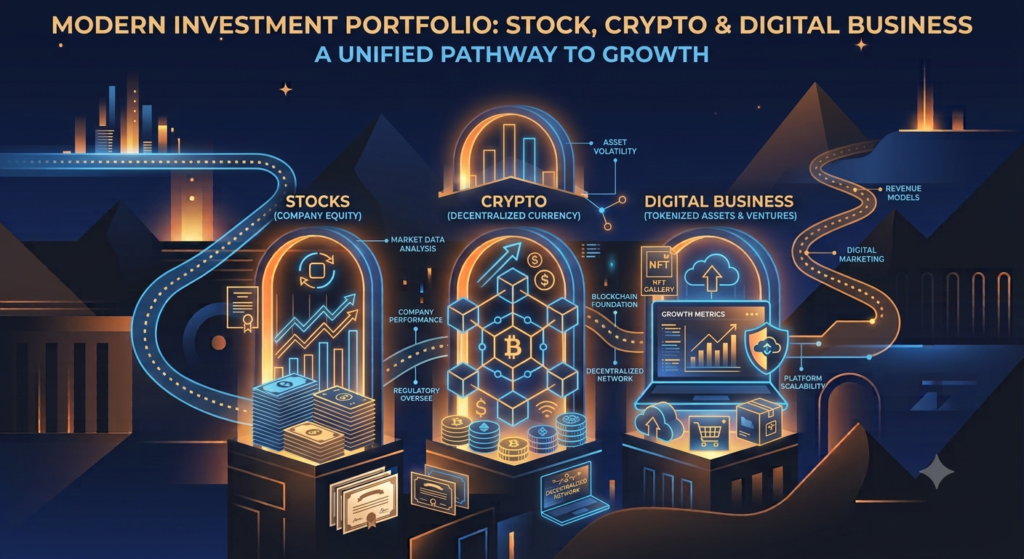
Seeing these three assets side by side makes it easier to understand why a balanced wealth building blueprint rarely relies on just one. Each asset class fills a different gap — stability, upside potential, or ownership-based income — and combining them is what makes a wealth building blueprint resilient across different market conditions.
| Factor | Stocks | Cryptocurrency | Digital Assets |
|---|---|---|---|
| Risk | Moderate | High | Moderate (execution risk) |
| Potential Returns | Moderate, steady | High, unpredictable | High, but effort-dependent |
| Volatility | Moderate | Very high | Low (income-based) |
| Liquidity | High | High | Low |
| Income Potential | Dividends, growth | Growth only (mostly) | Recurring passive income |
| Time Required | Low (after setup) | Low | High upfront |
| Beginner Friendliness | High | Moderate | Moderate |
| Long-Term Suitability | Strong | Uncertain | Strong (if built well) |
| Passive Income Potential | Moderate | Low | High |
Common Mistakes Beginners Make
Even with a solid wealth building blueprint in hand, certain habits can quietly undo months or years of progress. Watch for these patterns:
- FOMO investing — buying an asset only because everyone else is talking about it
- Chasing trends — jumping between “hot” stocks or coins instead of following a plan
- No diversification — putting most or all capital into one asset
- Emotional investing — panic-selling during downturns or over-buying during hype cycles
- Ignoring risk — not understanding how much you could realistically lose
- Investing money needed for bills — risking essential funds instead of using true discretionary capital
- Expecting overnight wealth — treating investing like a shortcut instead of a long-term process
Each of these mistakes shares a root cause: reacting to emotion instead of following a defined wealth building blueprint. Recognizing these patterns in yourself is often the first step to avoiding them.
How AI Is Changing Wealth Building
Artificial intelligence is reshaping several parts of the wealth-building process. AI-powered investing tools now help beginners analyze portfolios, track spending, and model long-term scenarios with far less effort than before. On the entrepreneurial side, AI is lowering the barrier to building digital businesses — from content creation to product development to customer support automation.
AI is also boosting personal productivity, allowing individuals to build digital assets faster than in previous years, whether that’s writing, design, or basic coding tasks.
For beginners following a wealth building blueprint, AI tools can meaningfully shorten the time it takes to complete Step 5 — building a digital asset — by handling research, first drafts, and repetitive production work. That frees up more time for the strategic decisions that actually shape a wealth building blueprint, like which niche to build in or how to price a digital product.
Still, AI should be viewed as a tool that supports sound investing principles, not a replacement for them. No algorithm can replace the discipline of consistent investing, proper diversification, and long-term patience. The fundamentals of a solid wealth building blueprint remain unchanged — AI simply makes execution more efficient.
Conclusion
Building real wealth isn’t about finding one perfect investment — it’s about following a complete wealth building blueprint that combines stocks, crypto, and digital assets in a balanced, intentional way. Stocks give you steady, historically reliable long-term growth. Crypto offers measured exposure to a high-risk, high-reward emerging asset class. Digital assets let you build genuine passive income through ownership and entrepreneurship.
None of these work in isolation. What creates lasting financial freedom is diversification, consistency, and the discipline to stay invested through both good years and bad ones. The beginners who succeed aren’t the ones who guess right every time — they’re the ones who follow their blueprint even when it’s boring.
Start small if you have to, but start today. Build your emergency fund, open a brokerage account, make your first index fund investment, and take the first step toward building a digital asset of your own. Your future wealth is built one consistent decision at a time.
Frequently Asked Questions
What is the best wealth building blueprint for beginners?
The best wealth building blueprint for beginners combines an emergency fund, consistent stock market investing through index funds or ETFs, a small and deliberate crypto allocation, and at least one digital asset for passive income. This combination balances stability with growth potential. Beginners should prioritize consistency over perfection, starting with whatever amount they can comfortably invest and increasing contributions as income grows. The goal isn’t to pick the single best investment — it’s to build a diversified system that keeps working even when one asset class underperforms.
Is it better to invest in stocks or crypto first?
Most financial educators recommend building a foundation in stocks before allocating meaningfully to crypto, since stocks are historically less volatile and represent ownership in real, cash-flow-generating businesses. Crypto can still play a role in a wealth building blueprint, but it should typically be a smaller, high-risk allocation added after your core stock investments are established. This order helps beginners avoid overexposure to an asset class known for dramatic price swings before they’ve built a stable investing foundation.
How much money do I need to start building wealth?
You don’t need a large sum to start building wealth. Many brokerages allow you to begin investing in index funds or ETFs with small, regular contributions. What matters more than the starting amount is consistency over time, thanks to the power of compound growth. Starting with even a modest amount and investing regularly often outperforms waiting until you have a “large enough” sum to begin, simply because time in the market matters more than timing the market.
What are digital assets in personal finance?
Digital assets are online properties or products that you own and that can generate income over time, such as websites, blogs, online courses, digital templates, software, or content channels. Unlike stocks or crypto, digital assets typically require upfront time and skill rather than just capital. Once built, they can produce recurring passive income while you retain full ownership, making them a valuable addition to a diversified wealth building blueprint, particularly for beginners with more time than investable capital.
Is cryptocurrency too risky for beginners?
Cryptocurrency carries significantly higher volatility than traditional stocks, which makes it riskier, but that doesn’t mean beginners should avoid it entirely. The safer approach is to treat crypto as a small, deliberate allocation within a broader wealth building blueprint rather than a primary investment. Beginners should only invest money they can afford to lose and avoid allocating a large portion of their savings to crypto based on hype or short-term price movements alone.
How does dollar-cost averaging work?
Dollar-cost averaging means investing a fixed amount of money at regular intervals, regardless of whether the market is up or down. Over time, this strategy smooths out the impact of market volatility because you buy more shares when prices are low and fewer when prices are high. It removes the pressure of trying to time the market perfectly, which even professional investors struggle to do consistently, and helps beginners stay disciplined during periods of market uncertainty.
What is the difference between active and passive income?
Active income requires your direct time and effort, such as a salary from a job or payment for freelance work — it stops when you stop working. Passive income comes from assets you own, such as dividend-paying stocks, rental income, or a digital product that continues generating revenue with minimal ongoing effort. A strong wealth building blueprint gradually shifts more of your financial picture toward passive income sources, since they build wealth independently of how many hours you personally work.